How to read your asset allocation
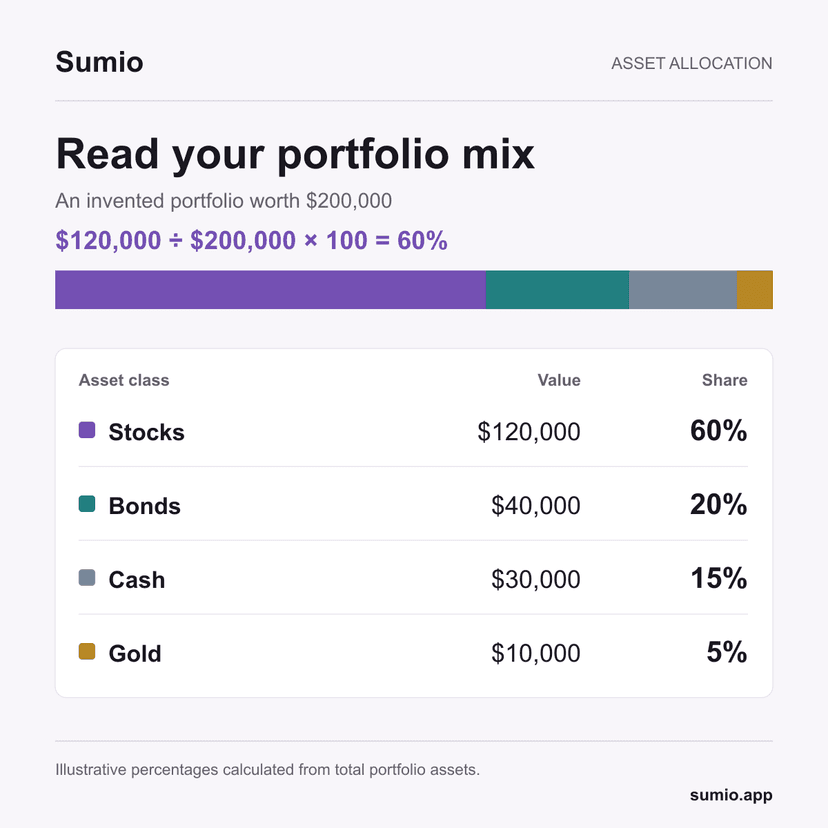
Asset allocation describes how you divide your investments among asset classes. The mix you choose depends on when you need the money and your ability to tolerate losses.

Practical guides on calculating net worth, valuing assets and liabilities, and tracking personal balance sheets without linking bank accounts.
A net worth simulator based on identical monthly cash outflow, solving break-even thresholds for property growth and investment returns.
Detailed breakdown of maintenance friction, file ownership, pricing, and when you should keep your spreadsheet.
An interactive due diligence checklist covering cash engines, all-in costs, statutory prospectuses, and regulator registers.
What to ask about management fee compounding, Form CRS and MiFID II disclosures, and how to spot evasive answers.
Asset allocation describes how you divide your investments among asset classes. The mix you choose depends on when you need the money and your ability to tolerate losses.

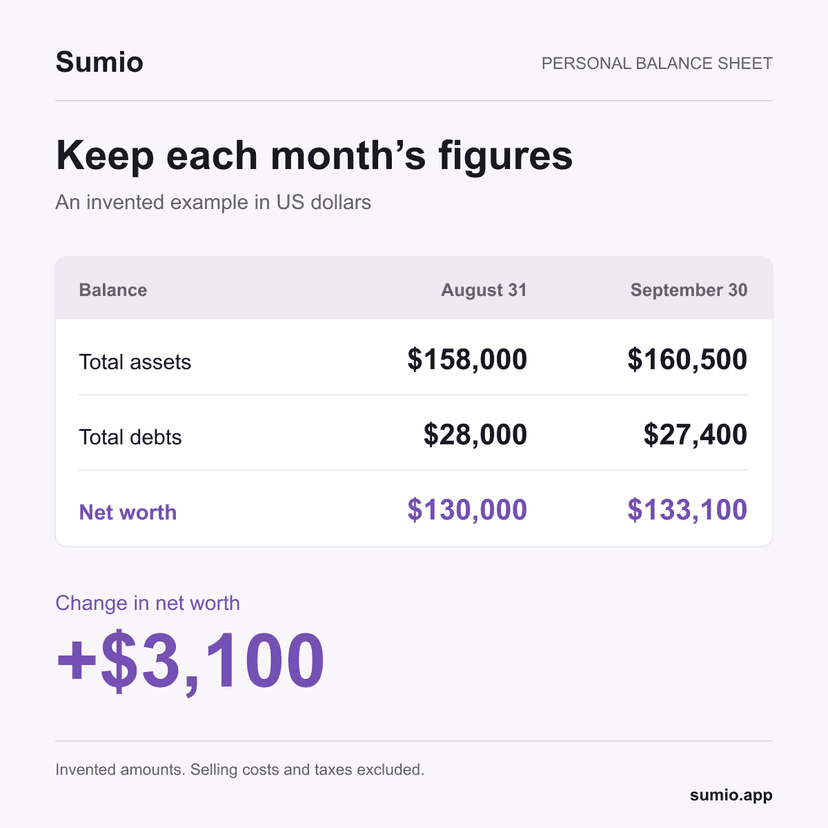
A personal balance sheet records the value of your assets and the debts you owe on a chosen date. Subtracting those debts gives your net worth, following the SEC's method for a net worth statement.

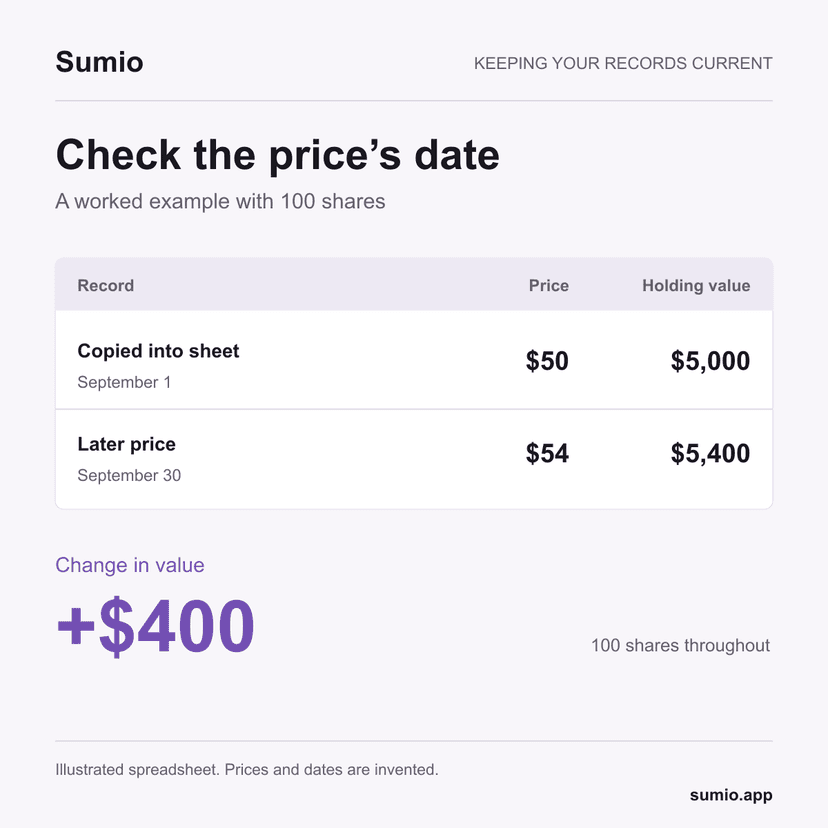
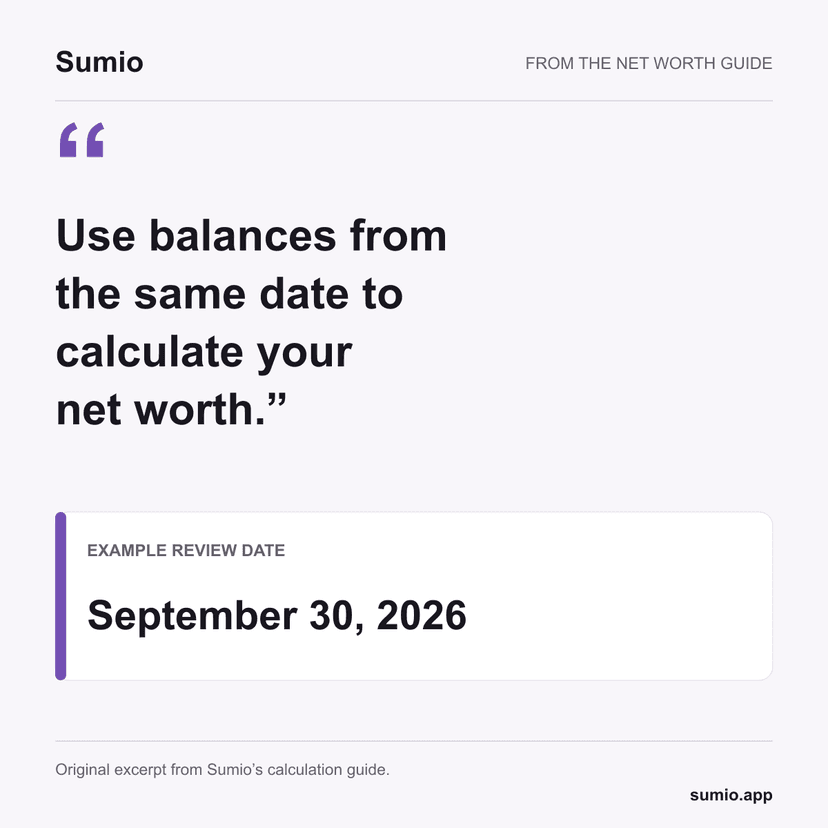
An exchange-traded fund (ETF) keeps trading after you copy its price into your net worth spreadsheet, so check the date behind that price when you next review the total.

To calculate your net worth, add up the current value of your assets and subtract your debts. A four-step method with current balances, debts, and currency conversion.

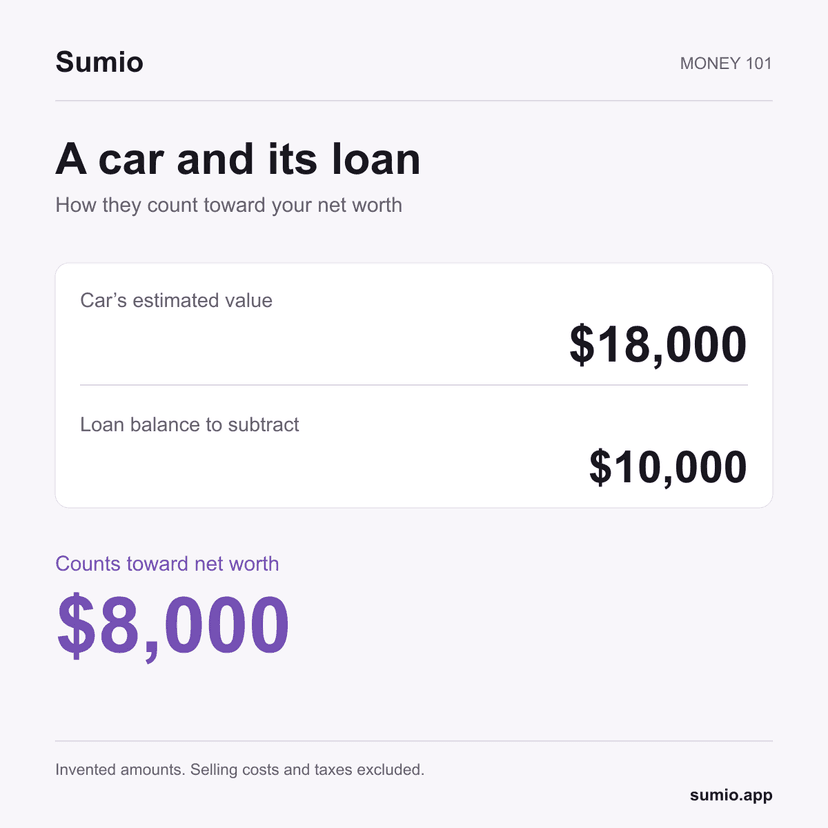
A car worth $18,000 belongs in your assets. If you owe $10,000 on the loan, that balance belongs in your liabilities. Together, the car and its loan contribute $8,000 to your net worth.

Your net worth is the current value of everything you own, minus everything you owe. Adding those balances together gives you a number you can follow over time.